Quick Answer
Yes, you can sell a condo with a pending special assessment in South Florida. The balance is usually settled at closing out of your proceeds. Cash home buyers in Miami can often close in 2 to 4 weeks, because they don’t need a lender to approve the building first.
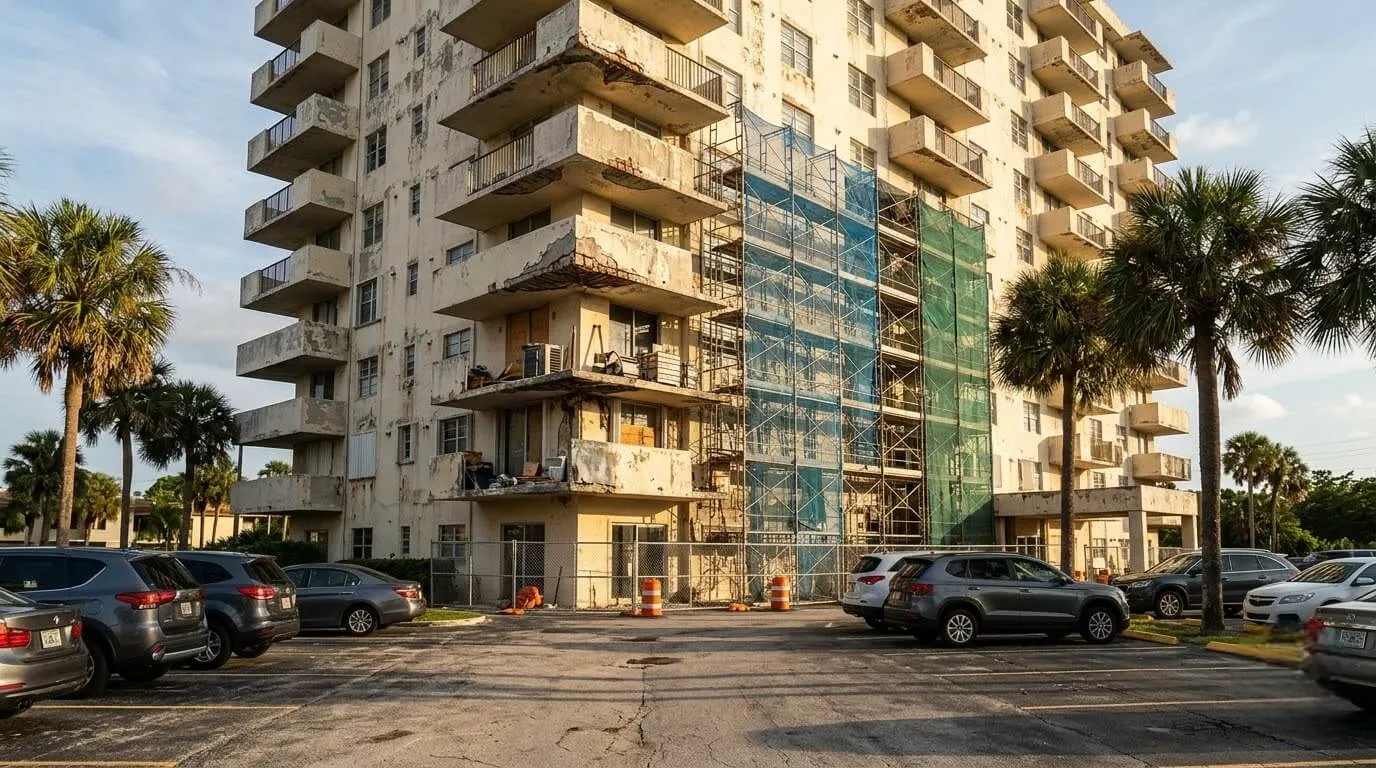
The letter from the board usually opens with “Notice of Special Assessment.” Then you get to the number. Sometimes it’s $20,000. Sometimes it’s $70,000. In a few older buildings near the water, it has gone past $100,000 per unit.
If you’re looking at cash home buyers in Miami because you can’t write that check (or you just don’t want to), this is for you. Below is how selling a condo with a pending assessment really works, who will buy it, and what to watch out for before you sign.
Why so many South Florida condos are getting these bills
After the Surfside collapse in 2021, Florida passed new condo safety laws. Buildings three stories or taller now need milestone inspections and a structural integrity reserve study, usually called a SIRS. The state later pushed the SIRS deadline to December 31, 2025.
The bigger change is about money. Associations can no longer vote to skip reserves for the major structural items, like the roof, load-bearing walls, and plumbing. When the reserves are short and the inspection finds work, the board covers the gap with special assessments, loans, or lines of credit. You can read the reserve rules in Florida Statute 718.112.
I’m not against the law. Surfside was a tragedy and the buildings needed the work. But 30 years of put-off maintenance landed on today’s owners all at once, and a lot of them are retirees living on a fixed income.
If you own in an older building in Brickell, Aventura, Sunny Isles Beach, North Miami Beach, Fort Lauderdale, or Hollywood, there’s a good chance your board is dealing with this right now.
Can you sell a condo with a special assessment pending?
Yes. An assessment doesn’t block a sale. It changes who can buy and how much they’ll pay.
- Buyers using a mortgage can run into trouble, because some lenders won’t finance units in buildings with big pending repairs or thin reserves.
- Every buyer will see the assessment in the association documents. You can’t hide it, and you shouldn’t try.
- Who pays depends on your contract. Many Florida contracts put assessments levied before closing on the seller, and that balance usually comes out of your proceeds at closing.
This isn’t legal advice. Have a Florida real estate attorney read your contract and the assessment notice.
Your options, side by side
| Option | Typical timeline | What happens with the assessment | Main risk |
|---|---|---|---|
| List with an agent | 60 to 120+ days | Paid from proceeds, or the price drops to cover it | A buyer’s lender rejects the building late in the deal |
| Sell to a local cash buyer | 2 to 4 weeks | Priced into the offer and settled at closing | Lower price than a perfect retail sale |
| Short sale | Several months | Negotiated with your lender and the association | Needs approval from both |
Condo closings usually take a bit longer than a house, because the association has to issue an estoppel certificate showing what’s owed. That’s normal, and a buyer who does this regularly will order it on day one.
How South Florida cash home buyers price a condo with an assessment
The math is the same one we use for houses. A buyer starts with what the unit would sell for in a healthy building, then takes out the assessment, any repairs inside the unit, and their margin.
Say your unit would sell for $280,000 in a building with full reserves. With a $45,000 assessment hanging over it, most retail buyers will knock at least that much off, and some will walk away completely. A cash buyer runs the same numbers, but can close without waiting on a lender to approve the building.
That’s how we price condos at Antlop, the same way we do as cash home buyers in South Florida for single-family homes. If you want to see how cash offers compare with market value in general, I broke that down in what cash buyers actually pay vs. market value.
Got an assessment letter you can’t pay?
Get a fair cash offer on your condo within 24 hours. We buy units across Miami-Dade, Broward, and Palm Beach, assessment and all.
Talk to cash home buyers in Miami who actually close on condos, not a call center.
Get My Free Cash OfferAsk your association for these documents first
Whether you sell to us, list with an agent, or decide to stay, get these in hand. They tell you how bad things are and whether more bills are coming.
- The current structural integrity reserve study (SIRS)
- The milestone inspection report, including any Phase 2 findings
- This year’s budget and reserve schedule
- The last 12 months of board meeting minutes
- The assessment notice, with the amount, due dates, and any payment plan
- An estoppel certificate showing your current balance
Board minutes are the part most owners skip. They’re also where you’ll find out if a second assessment is already being discussed.
Pay the assessment and stay, or sell now?
| Factor | Pay and stay | Sell now |
|---|---|---|
| Cash you need today | The full assessment, or a loan or payment plan | None. It comes out of your proceeds at closing |
| Future assessments | You’re on the hook if the SIRS shows more work | Not your problem after closing |
| Monthly dues | Likely to rise as reserves get funded | Stop at closing |
| Makes sense if | You love the unit and can afford the bills | The numbers don’t work or you’re ready to move on |
If you owe more than the condo is worth
Sometimes the assessment pushes a unit underwater. If your mortgage plus the assessment is more than the condo will sell for, a straight cash sale may not cover it.
That’s where a short sale comes in. Your lender agrees to take less than the full balance, and the association has to sign off on its share too. We handle both sides for owners in Fort Lauderdale, Hollywood, Pompano, and the rest of the county. Here’s how we work with condo owners as cash home buyers in Fort Lauderdale and across Broward.
And if your unit isn’t underwater, it’s simpler. We buy houses in Broward County the same way we do in Miami-Dade: as-is, for cash, with no commission.
Watch out for these red flags
Condo owners with big assessments get a lot of calls from “cash buyers in Miami” who found their name in public records. Some are fine. Some are wholesalers who will tie up your unit with a contract and try to sell that contract to someone else.
- Ask who is actually buying the unit and whose name will be on the deed.
- Ask for proof of funds before you sign.
- Walk away from anyone asking for a fee up front or pushing you to sign today.
FAQ
Do I have to pay the special assessment before I sell?
Not before. In most sales, whatever you owe on the assessment is paid at closing out of your proceeds. Your contract decides the details.
Can a buyer take over my assessment payments?
Sometimes. If the board approved a payment plan, the buyer and seller can agree on who covers the remaining installments. Put it in writing in the contract.
Do cash home buyers in Miami buy condos in older buildings?
Yes. We buy units in older buildings, including ones with pending milestone work, across Miami-Dade, Broward, and Palm Beach.
Does the SIRS law apply to my townhouse or house?
It’s aimed at condo buildings three stories or taller. It generally doesn’t apply to single-family homes, and most townhomes aren’t covered either. Check with your association to be sure.
The bottom line
A special assessment doesn’t trap you. You can pay it and stay, list and let the price absorb it, or sell to cash home buyers in Miami who close without a lender judging the building. Get the association documents first, run your numbers, and then decide.
Cash Home Buyers in Miami
Ready to Sell Your Condo Before the Next Bill?
Get a free, no-obligation cash offer today. We close on your schedule, assessment and all.
Get My Free Cash Offer Now (305) 501-0457“Se Habla Español” · No fees, no commissions, no obligation