“How much cash will I get for my house in Miami-Dade County?” is usually the first question homeowners ask, and understandably so, as it is the number everything else depends on. The honest answer is that it varies more than most people expect, and it is rarely just a percentage knocked off what a real estate agent might list the property for. A genuine cash offer is built from several moving parts, and once you understand what they are, the number stops feeling arbitrary.
What Actually Goes Into a Cash Offer
A fair cash offer starts with the property’s current market value, based on what comparable sales (“comps”) nearby have recently achieved, not simply active MLS asking prices, since listing prices and final closing prices often drift apart. From there, an investor works backward, accounting for the cost of repairs and renovations, the holding costs (such as property taxes, insurance, and HOA fees) incurred while preparing the home for resale, and a reasonable margin for taking on that investment risk.
That is the difference between a cash offer and a traditional listing in a single sentence: with a real estate agent, you may sell closer to full market value, but you carry the out-of-pocket repair costs, months on market, and financing contingencies yourself. With a direct cash sale, you accept a discount below peak retail value, but the buyer absorbs the inspection repairs, holding timeline, and market risk instead.
The Main Factors That Move the Number
- Location within Miami-Dade County: Property values vary significantly between submarkets such as Miami Lakes, Hialeah, Doral, Coral Gables, and Miami Gardens. Two comparable single-family homes just a few miles apart can yield substantially different offers.
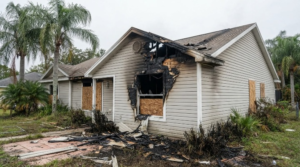
- Property Condition: A residence requiring a full roof replacement, updated electrical panels, cast-iron pipe replacement, or structural remediation will see those capital expenditures subtracted directly from the valuation.
- Title Issues, Back Taxes, and Mortgage Balances: Any municipal liens, delinquent property taxes, or existing mortgage payoffs must be settled out of seller proceeds at closing, regardless of transaction type.
- Closing Timeline: A rapid closing often influences pricing parameters, as accelerated timelines alter capital allocation and holding schedule projections.
- Occupancy Status: Whether the home is tenant-occupied, vacant, or subject to pre-foreclosure proceedings dictates distinct operational costs, legal processes, and buyer risks.
Cash Sale vs. Traditional Agent Sale
| Factor | Cash Sale (Direct Buyer) | Traditional Agent Sale |
|---|---|---|
| Typical Sale Price | Below retail market value | Closer to full market value |
| Commissions and Broker Fees | None | Typically 5% to 6% of sales price |
| Repair and Renovation Costs | Covered entirely by buyer (“as-is”) | Usually paid by seller prior to closing |
| Time to Close | 7 to 21 business days | 45 to 90+ days |
| Financing Contingency Risk | Minimal (no mortgage underwriting) | Higher (appraisal and loan denial risks) |
Once you subtract brokerage commissions, seller concessions, professional home staging, and monthly carrying costs (mortgage payments, hazard insurance, utilities) associated with standard marketing periods, the net walkaway difference between both routes is often narrower than sellers anticipate.
If you want a definitive answer on your potential proceeds in Miami-Dade County, the only accurate method is securing an individualized property evaluation.
What About Liens, Delinquent Taxes, or a Short Sale?
If you owe more on the mortgage balance than current fair market value, or if municipal code violations and unpaid tax certificates encumber the title, a standard cash buyout may not extinguish all encumbrances. In this event, an approved short sale could represent the proper route. This does not preclude a transaction; rather, it requires structuring the transaction through lender loss mitigation rather than standard equity disbursement. An experienced South Florida short sale specialist can navigate servicer approvals and outline your options before executing legal agreements.
How to Get an Accurate Figure, Not an Estimate
Automated valuation models (AVMs) and broad algorithmic estimates cannot capture deferred maintenance or hyper-local neighborhood factors. The only dependable method to establish direct cash value is an on-site property walkthrough to evaluate physical condition, title history, and municipal status, culminating in a firm written purchase agreement. This clarity provides the exact numbers required to weigh a direct sale against an MLS listing.
A formal cash assessment involves no obligations and no associated inspection costs. It delivers a verifiable baseline to guide your selling decision.
Frequently Asked Questions
How much cash will I get for my house in Miami-Dade County?
It depends on the home’s value based on recent comparable sales, what repairs it needs, the holding costs the buyer takes on, and what is still owed on the property. The only way to get a firm number is a walkthrough followed by a written offer.
Do I pay fees or commissions when I sell my house for cash?
Not when you sell to Antlop. We cover the closing costs and charge no fees or commissions, so the offer you accept is the amount you receive. Mortgage payoffs, liens, and unpaid property taxes still come out of your proceeds at closing, the same as they would in any sale.
Do I need to make repairs before I sell?
No. In an as-is sale, the buyer takes the house in its current condition, including deferred maintenance, fire damage, or mold. You don’t fix anything first.
How fast can I close on a cash sale?
Most cash sales close within 7 to 21 days of the first call. Title issues, whether the home is occupied, and whether an HOA estoppel letter is needed can stretch that timeline.
What if I owe more than my house is worth?
A standard cash sale may not cover everything owed. A short sale is often the more realistic route, where your lender agrees to accept less than the full loan balance. A short sale specialist can walk you through the numbers before you sign anything.
Can I still sell if I’m behind on payments or in foreclosure?
Yes. Being behind on payments or already in foreclosure does not stop you from selling. A cash sale or short sale can often still close before a scheduled foreclosure sale date.
Find Out How Much Cash You’ll Get for Your House in Miami-Dade County
Sell house for cash Miami with no fees, no commissions, no repairs, and a written offer within 24 hours.
Antlop Investment Properties has acquired more than 200 residential properties directly across Miami-Dade, Broward, and Palm Beach counties since 2012, utilizing private balance-sheet capital and holding long-standing standing with the Broward Real Estate Investors Association (BREIA). Request a transparent, no-obligation valuation for your property today.
Get My Fair Cash Offer →